
It’s been a year of disruption in New Zealand’s loyalty landscape, with newly packaged Koru Club and Club+ programmes, intensified supermarket competition and consumers continuing to navigate a stubborn cost-of-living squeeze. With this in mind, you might expect Kiwi enthusiasm for loyalty programmes to be on the down; but it isn’t.
For the third year running, Quantum Jump partnered with research specialist Yabble to assess New Zealand’s loyalty market. In August 2026 we surveyed 750 New Zealanders aged 18+, nationally representative by age, gender and region, each a member of at least one loyalty or reward programme.
Appetite for loyalty is high amongst consumers.
Everyday Rewards is dominating coalition programmes.
Consumers appreciate both digital and physical access to loyalty programmes.
Digital expectations are climbing but email still rules for comms.
Up from 2024 and 2025, 80% of Kiwis feel positive about loyalty programmes, while the share who consider them a waste of time is below 2%. Among under-35s, positivity reaches a remarkable 91%.
Positive sentiment is one thing, but influence on behaviour is another. This is where the data really matters for brands.
Loyalty is no longer just the preserve of retention teams, but has become an acquisition lever alongside this. 46% of Kiwis say a loyalty programme influences a first-time purchase decision (59% under 35 y/o), and 55% say it influences whether they stay with a company.
When asked to name their top programmes, Kiwis are remarkably consistent. Everyday Rewards leads the pack, named in the top three by 65%, Club+ sits in second place at 50%, followed by Air New Zealand Koru at 47%.
Everyday Rewards is doing three things very well: it is ubiquitous; it is perceived as genuinely generous; and it is unapologetically app-forward. This combination is a reminder that scale, value and digital execution compound on each other.
Core mechanics still matter most in loyalty, Top benefits for Kiwi are earning points/dollars to redeem on things (86%) and getting instant discounts (85%). These are followed at a distance by “surprise and delight” freebies (43%), competitions (27%), better experiences such as faster delivery (21%) and exclusive products or events (21%).
Three deeper currents, however, are reshaping expectations.
Email is the preferred channel, chosen by 79% of Kiwis as one of their top two preferred ways to hear from a loyalty programme, well ahead of app notifications (29%), text (17%), messaging (6%) or direct mail (5%).
That is one of the largest opportunity gaps in the entire dataset. Most brands are overlooking how direct, relevant, well-timed communication is what turns a transactional rewards mechanic into a relationship.
43% of Kiwi place “occasional freebies” in their top benefits. This is a meaningful signal that purely transactional programmes are starting to feel commoditised. Tiers are powerful here too: 52% of under 35s say tier mechanics motivate them to engage more, compared with just 13% of over-65s, suggesting younger Kiwis are increasingly comfortable with status as a reward in its own right. And under-35s are notably more open than older cohorts to paying a subscription fee for elevated loyalty benefits (23%) compared to over-65s (1%).
There’s always been a bigger factor nagging in the back of our minds in our loyalty reporting – awareness and accessibility naturally skew many results towards the bigger, national more established programmes.
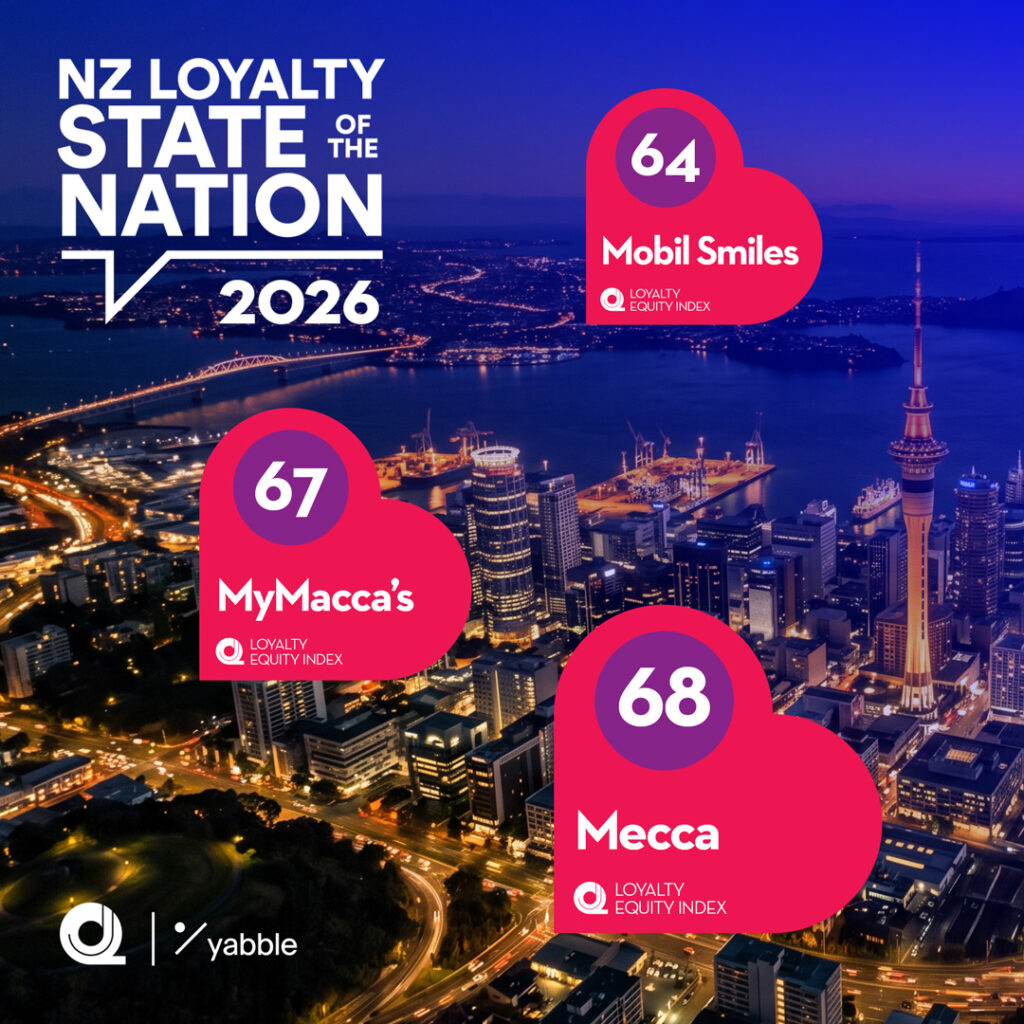
But this doesn’t necessarily mean people like them more! So we’ve developed a metric for the holistic impact of a loyalty programme on a customers’ relationship with the brand.
The Loyalty Equity Index (scored 1–100) is built to evaluate performance across three dimensions: Behavioural intent, advocacy and emotional attachment.
Three strategic imperatives stand out for any New Zealand business thinking about how to compete on customer relationships over the next 18 months.
Mobile-first, app-led programmes that integrate into daily routines (grocery, payment wallets, travel) are now the benchmark. Personalisation and real-time offers need to layer on without overwhelming the user.
At the same time, digital-only thinking risks alienating the audience with the most money to spend. Hybrid models like apps plus email, plus physical cards, plus genuine human service will outperform pure-digital plays in the economically important 45+ cohort.
Given that email remains the channel of choice for 79% of Kiwis, the brands that win the next two years will be those that elevate loyalty communication to the same standard as their advertising. That means real personalisation, relevance, timing, and a genuine investment in the editorial skill of the customer message.
Generative and agentic AI agents are beginning to act as intermediaries in search and shopping, recommending “best value” products without any loyalty bias. AI-driven shopping assistants can quietly reduce brand visibility for those without strong pre-existing loyalty or subscription relationships.
Three defences will matter. First, deeper first-party data strategies, so brands can personalise in ways an AI agent cannot replicate. Second, genuinely emotional loyalty with surprise, delight, exclusivity and recognition. Third, membership ecosystems that span multiple categories, making it harder for an AI to swap a brand out without breaking value the customer already enjoys.
Quantum Jump is New Zealand’s specialist loyalty agency. Our team has helped design, launch and nurture some of the country’s most iconic programmes: New World Clubcard, Mitre 10 Club, Sky Rewards, Subcard, and Farmers Club. We bring strategic, creative and data-driven thinking to loyalty, CRM, CX and marketing automation.
Ben Goodale, CEO
METHODOLOGY
Quantitative survey of 750 New Zealanders aged 18+, conducted by Yabble for Quantum Jump in August 2026. Sample nationally representative by age, gender and region. Respondents were required to be a member of at least one loyalty or reward programme (self-defined). Year-on-year comparisons reference the equivalent 2025 study.
© Quantum Jump & Yabble 2026. Insights may be cited with attribution.